Introduction
The UK retail sector has undergone major changes since 2020, with pandemic disruption, inflation, changing consumer behaviour, digital commerce, discount retail, and evolving store strategies reshaping competition. Retailers now compete across physical stores, websites, marketplaces, mobile channels, loyalty ecosystems, and increasingly data-driven pricing models. According to the Office for National Statistics (ONS), Great Britain retail sales volumes increased 1.3% in 2025 after a 0.2% increase in 2024, although volumes remained below pre-pandemic levels.
This report examines the Top 20 largest retail chains in the UK 2026 through revenue, market positioning, store presence, grocery leadership, digital expansion, and competitive intelligence. UK market Data provides the broader context for understanding how leading retailers are adapting to changing demand. Because a single authoritative source does not publish one definitive ranking of all UK retail chains by 2026 revenue, the analysis below uses industry indicators and retailer-level intelligence as a strategic framework rather than presenting an unsupported universal ranking.
Mapping the Leaders Across Britain's Retail Landscape
Scrape Largest UK Retail Chains 2026 can help businesses build structured datasets covering retailer names, categories, product ranges, prices, promotions, stores, online assortment, availability, and competitive positioning. For market research, retailer-level data can be combined with official statistics to understand how the industry has evolved from 2020 through 2026.
The pandemic produced a significant shift toward online purchasing in 2020 and 2021. ONS data shows the non-store retailing value index rose from 89.4 in 2020 to 105.8 in 2021 before settling at 104.8 in 2025. This illustrates why digital channels remain an important component of modern retail intelligence.
| Year |
Retail Sales Volume Change |
Market Development |
| 2020 |
Pandemic disruption |
Rapid shift toward online retail |
| 2021 |
Strong digital demand |
Non-store retail reached elevated levels |
| 2022 |
Decline |
Cost pressures and reopening affected volumes |
| 2023 |
Decline |
Consumers faced continued affordability pressure |
| 2024 |
+0.2% |
Retail volumes began recovering |
| 2025 |
+1.3% |
Second consecutive annual volume increase |
| 2026 |
Ongoing |
Competition remains focused on value and omnichannel retail |
The 2026 market therefore needs to be viewed as an interconnected ecosystem rather than a simple store-count competition. Major grocery chains compete through convenience, loyalty pricing, private-label products, and online delivery, while fashion, home improvement, general merchandise, and specialist retailers increasingly combine physical stores with digital channels. A structured retail dataset can help brands benchmark these differences and identify where competitive pressure is strongest. ONS continues to publish retail sales in both value and volume terms, providing an official baseline for interpreting retailer performance.
Understanding Revenue Scale and Retailer Influence
Analysing the biggest UK retail chains by revenue requires separating revenue from market share. A retailer can have significant revenue because of its category, product mix, international operations, or business model, while another may have stronger UK market share within a specific category. This distinction is especially important when comparing grocery chains with fashion, home improvement, electrical, or general merchandise retailers.
The broader retail environment from 2020 to 2026 shows why revenue alone cannot explain competitive strength. During the pandemic, online retail gained exceptional importance. In subsequent years, physical retail recovered while online channels remained structurally important. ONS reported that non-store retail volumes peaked in 2021 and subsequently moderated, although they remained an important component of the market.
| Year |
Key Revenue Environment |
Strategic Priority |
| 2020 |
Disrupted physical retail |
Digital availability |
| 2021 |
Elevated online demand |
Omnichannel expansion |
| 2022 |
Inflationary pressure |
Value positioning |
| 2023 |
Weak retail volumes |
Cost efficiency |
| 2024 |
Early volume recovery |
Customer retention |
| 2025 |
1.3% volume growth |
Value and convenience |
| 2026 |
Competitive recovery |
Data-led optimisation |
Revenue research should therefore consider UK sales, group revenue, category exposure, store networks, digital sales, and international operations separately. Retailers such as Tesco, Sainsbury's, Asda, Aldi, Lidl, Morrisons, M&S, Kingfisher, B&M, Next, and other large operators can occupy very different competitive positions.
For brands selling through these retailers, structured data extraction can reveal how products are positioned across channels. Price comparisons, assortment breadth, promotional intensity, availability, and product visibility can complement financial metrics and provide a more complete picture of retail competitiveness.
Comparing Retail Leaders Through Multiple Performance Indicators
The concept of Largest UK Retailers by Revenue 2026 should not be reduced to a single financial number. A useful competitive assessment combines revenue scale with store footprint, online presence, category strength, customer reach, pricing strategy, and market share. This is particularly relevant because retail companies increasingly operate through multiple channels.
The years 2020–2026 demonstrate the importance of this multidimensional approach. Physical retail was heavily disrupted in 2020, online purchasing expanded in 2021, inflation reshaped consumer priorities in 2022 and 2023, and retail volumes began recovering during 2024 and 2025. ONS reported that 2025 retail volumes increased 1.3%, following a 0.2% increase in 2024.
| Year |
Primary Competitive Factor |
Retailer Response |
| 2020 |
Accessibility |
Online fulfilment |
| 2021 |
Digital reach |
E-commerce investment |
| 2022 |
Inflation |
Value pricing |
| 2023 |
Consumer affordability |
Promotions and private label |
| 2024 |
Recovery |
Omnichannel optimisation |
| 2025 |
Volume growth |
Loyalty and convenience |
| 2026 |
Competitive intensity |
Personalisation and analytics |
For competitive analysis, retailers can be evaluated through several dimensions: annual revenue, UK-specific revenue where available, number of locations, digital presence, market share, product assortment, pricing competitiveness, and customer engagement.
This approach is particularly useful for businesses supplying major retailers. A supplier may discover that a retailer with fewer physical locations has stronger digital visibility, while a large store network may indicate greater geographic reach. Combining these indicators with product-level data allows companies to understand not just who is large, but why a retailer is commercially influential.
Grocery Competition and the Changing Value Equation
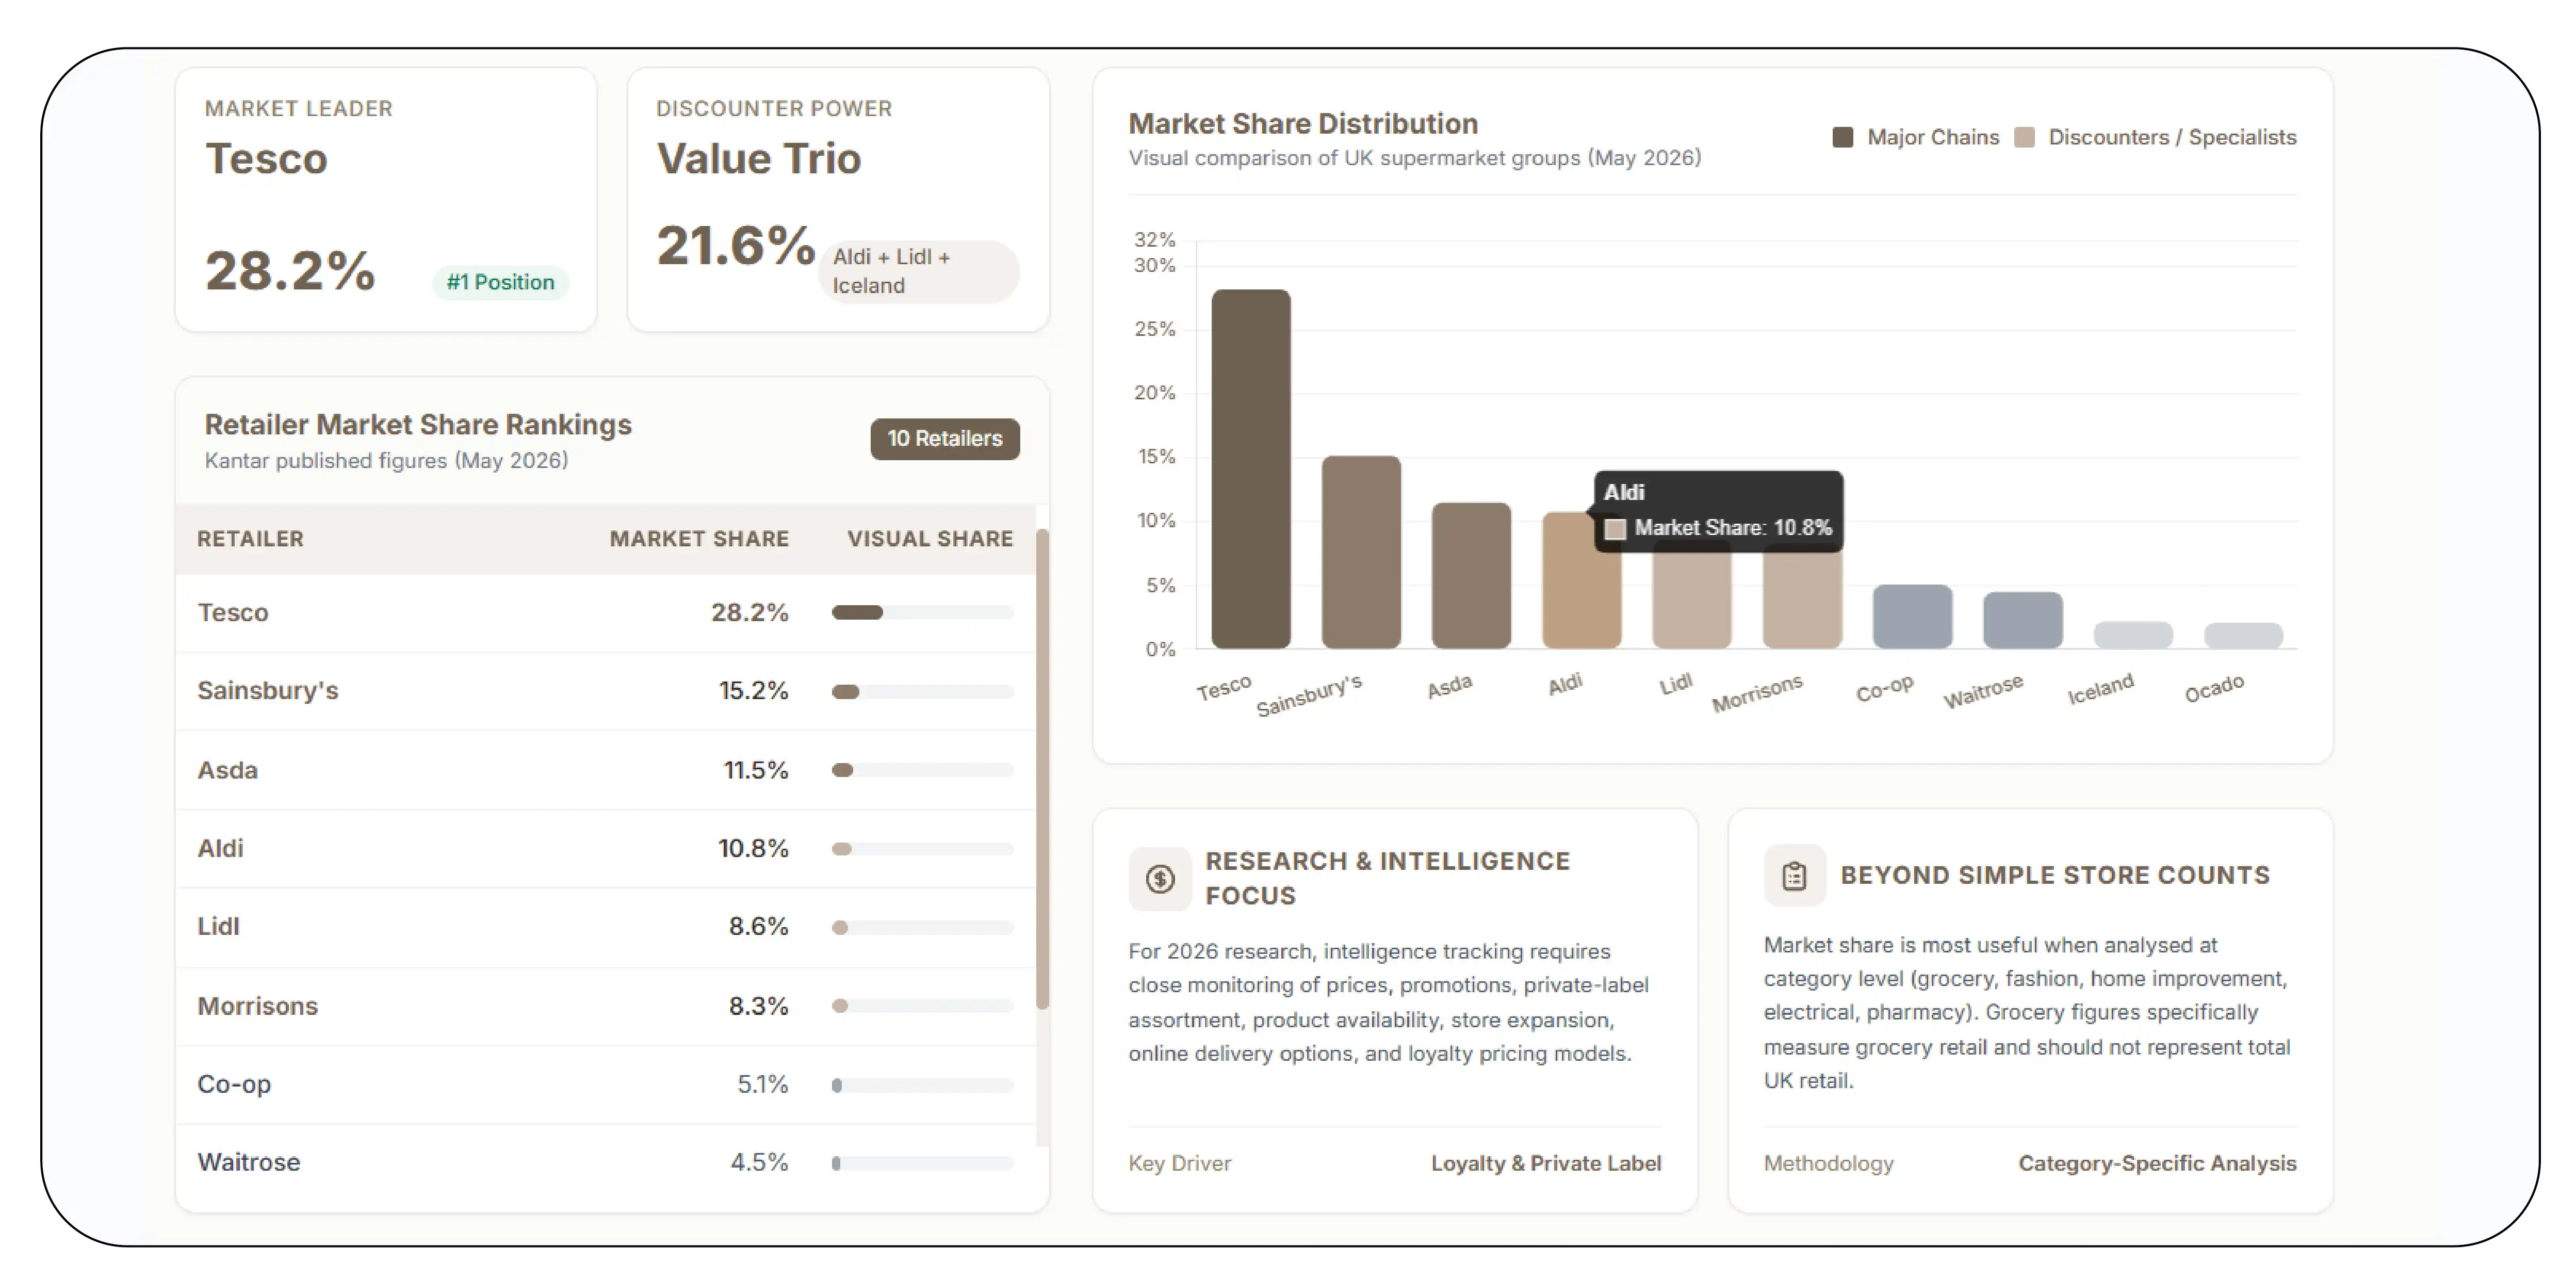
The UK supermarket chains ranked 2026 continue to represent one of the most important parts of the country's retail landscape. Grocery competition illustrates how market share, store networks, pricing, private-label strategies, loyalty programmes, and convenience influence consumer behaviour.
The latest government-published Kantar figures for the 12 weeks ending 17 May 2026 show Tesco leading UK grocery market share at 28.2%, followed by Sainsbury's at 15.2%, Asda at 11.5%, Aldi at 10.8%, Lidl at 8.6%, and Morrisons at 8.3%. The four largest food and drink retailers together held 65.7% of the grocery market.
| Retailer |
Grocery Market Share – May 2026 |
| Tesco |
28.2% |
| Sainsbury's |
15.2% |
| Asda |
11.5% |
| Aldi |
10.8% |
| Lidl |
8.6% |
| Morrisons |
8.3% |
| Co-op |
5.1% |
| Waitrose |
4.5% |
| Iceland |
2.2% |
| Ocado |
2.1% |
These figures demonstrate the importance of value competition. Aldi, Lidl, and Iceland collectively held 21.6% of grocery market share in the cited period.
For 2026 research, grocery intelligence should therefore track prices, promotions, private-label assortment, availability, store expansion, online delivery options, and loyalty pricing. These indicators help explain why individual retailers gain or lose share. For brands and suppliers, monitoring the grocery leaders can also reveal which retailers are expanding specific categories and where pricing pressure is increasing.
Measuring Market Share Beyond Simple Store Counts
UK Retail Market Share 2026 is most useful when analysed at category level rather than treating the entire retail industry as one market. Grocery, fashion, home improvement, electrical, pharmacy, general merchandise, and online retail have different competitive structures. A retailer can dominate one category while having limited influence in another.
The grocery market provides a clear example. Tesco held 28.2% of the grocery market in the 12 weeks ending 17 May 2026, while Sainsbury's held 15.2%. However, these figures should not be used as total UK retail market shares because the methodology specifically measures grocery retail.
| Indicator |
2020–2021 Trend |
2022–2024 Trend |
2025–2026 Direction |
| Online retail |
Strong expansion |
Normalisation |
Established channel |
| Grocery |
Essential spending |
Value pressure |
Competitive pricing |
| Discount retail |
Growing importance |
Continued expansion |
Strong market position |
| Fashion |
Digital disruption |
Recovery |
Omnichannel competition |
| Home improvement |
Pandemic boost |
Normalisation |
Selective demand |
| General merchandise |
Online growth |
Competitive pricing |
Convenience-led |
The ONS internet-sales series shows how online retail remains structurally significant. The proportion index for non-store retailing was 81.9 in 2020, rose to 91.7 in 2021, and stood at 89.0 in 2025.
This makes omnichannel intelligence essential. Retailers need to understand not only store presence but also digital assortment, online prices, product availability, delivery options, and promotional activity. A comprehensive dataset can connect these signals and provide a more accurate representation of competitive market position.
Geographic Scale, Store Networks, and Omnichannel Reach
A multi-location retail chain can generate competitive advantages through geographic coverage, brand recognition, local availability, and physical customer access. However, store count alone does not determine retail strength. The modern retailer combines locations with e-commerce, fulfilment infrastructure, loyalty programmes, mobile engagement, and marketplace visibility.
The Top 20 largest retail chains in the UK 2026 should therefore be assessed using a combination of physical and digital indicators. A useful framework includes revenue, number of stores, geographic coverage, online presence, market share, product categories, average price positioning, and promotional intensity.
| Year |
Store Network Priority |
Digital Priority |
| 2020 |
Essential access |
Rapid online expansion |
| 2021 |
Hybrid shopping |
E-commerce scale |
| 2022 |
Network optimisation |
Digital efficiency |
| 2023 |
Cost-efficient locations |
Personalisation |
| 2024 |
Omnichannel integration |
Loyalty ecosystems |
| 2025 |
Convenience and proximity |
Data-driven offers |
| 2026 |
Integrated store network |
Real-time retail intelligence |
Retailers with large geographic networks can use stores as fulfilment points, collection locations, and customer engagement centres. Digital channels can then extend reach beyond traditional catchment areas. This creates a more complex competitive environment in which store density and online availability interact.
For market researchers, monitoring these changes can reveal expansion strategies and competitive gaps. For suppliers, it can indicate where products have broader distribution potential. For brands, it can highlight which retailers are gaining visibility in specific categories. Combining store-level information with product and pricing data therefore provides a stronger foundation for understanding retail competitiveness in 2026.
Why Choose Product Data Scrape?
Product Data Scrape helps businesses build structured retail intelligence systems that combine product, pricing, availability, assortment, and competitive information. Retailers and brands can use automated data collection to monitor competitors, categories, products, and locations at a scale that is difficult to achieve through manual research.
The platform can support businesses seeking to understand how retailers to predict consumer demand by creating datasets that reveal product availability, pricing movements, assortment changes, promotions, and market activity. Historical observations can be combined with current data to identify recurring patterns and changes in consumer-facing retail behaviour.
For businesses researching the Top 20 largest retail chains in the UK 2026, this approach can support retailer benchmarking across categories and channels. Data can be structured for dashboards, market research, competitive intelligence, pricing analysis, assortment monitoring, and demand forecasting.
Product Data Scrape can also support recurring workflows, allowing businesses to establish monitoring schedules based on category importance and data volatility. This creates a repeatable data pipeline rather than disconnected research exercises. The result is a stronger foundation for understanding retailer positioning, competitor strategies, product availability, and evolving market opportunities.
Conclusion
The UK retail market in 2026 reflects several years of structural change. Pandemic-driven digital adoption, inflation, affordability concerns, discount expansion, omnichannel investment, and changing consumer expectations have all influenced competitive positioning. ONS data shows retail volumes grew 1.3% in 2025 after 0.2% growth in 2024, although the overall market remains shaped by the longer-term effects of the pandemic and changing shopping behaviour.
The grocery sector remains particularly concentrated, with Tesco leading at 28.2% market share in the latest May 2026 Kantar figures published by the UK government, followed by Sainsbury's at 15.2%.
Understanding the leading retailers therefore requires more than revenue rankings. Businesses need visibility into pricing, assortment, stores, digital channels, promotions, availability, and consumer-facing market signals.
Retail intelligence enables companies to turn these signals into structured insights for competitive benchmarking, market research, pricing, assortment planning, and demand forecasting. The Top 20 largest retail chains in the UK 2026 can serve as a starting point for building a broader retailer-monitoring framework.
Want to benchmark leading UK retailers with structured, continuously refreshed data? Connect with Product Data Scrape to build a retail intelligence solution tailored to your market research and competitive analysis needs!


 Singapore
 EMAIL
 PHONE






.webp)